
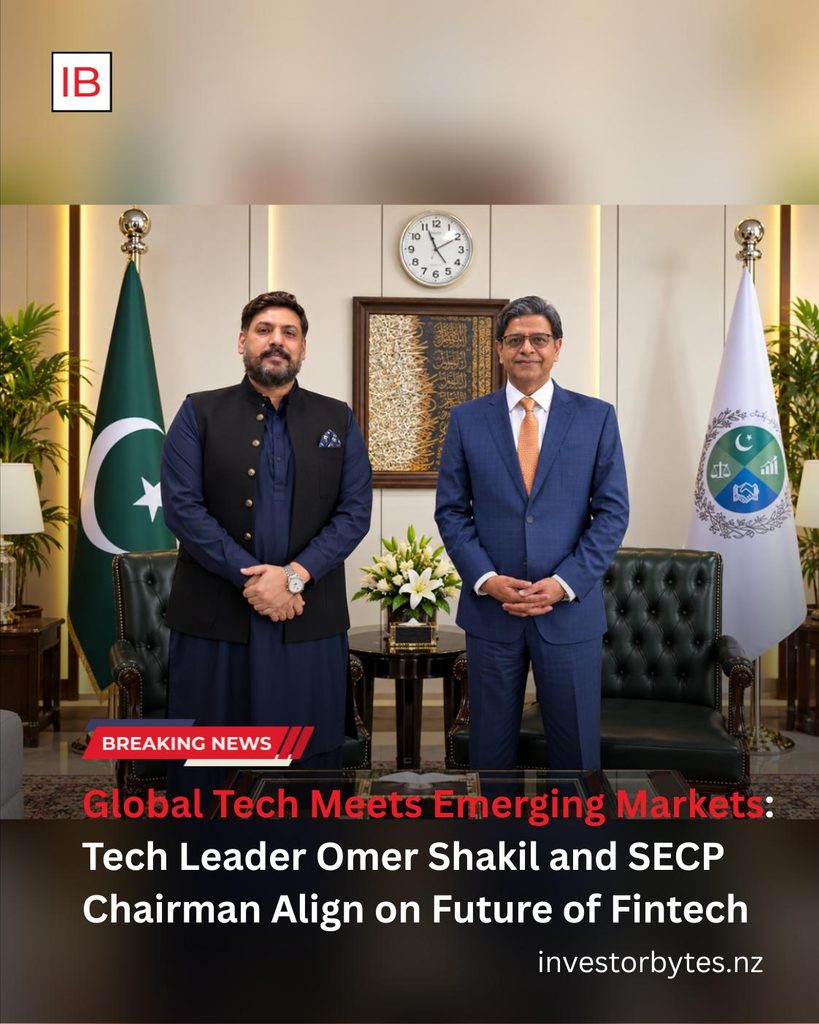
Discover 5 SECP fintech breakthroughs shaping Pakistan’s financial future, from digital finance and investor access to powerful fintech innovation and growth.
Discover 5 SECP fintech breakthroughs shaping Pakistan’s financial future, from digital finance and investor access to powerful fintech innovation and growth.
SECP fintech development is becoming an increasingly important part of Pakistan’s financial transformation, with digital investor onboarding, technology-enabled lending and innovative financial services creating new opportunities across the country’s financial ecosystem.
SECP has introduced digital onboarding initiatives and continues to develop frameworks for technology-enabled financial services.
SECP Fintech Revolution Gains Momentum
The Securities and Exchange Commission of Pakistan (SECP) is increasingly focusing on technology-enabled financial services. Digital onboarding, API integration and innovative financial solutions are helping create a more accessible and connected financial ecosystem.
These developments could make financial services easier to access while encouraging fintech companies to develop new solutions for Pakistan’s growing digital economy.
Table of Contents
1. Digital Investor Onboarding
One of the most important developments in SECP fintech is the move toward digital investor onboarding.
Technology can simplify the process of opening investment accounts by reducing paperwork and allowing investors to complete more steps digitally. SECP’s framework for digital onboarding through financial institutions and third parties using API integration is part of this broader transformation.
For investors, faster digital onboarding can make participation in regulated financial markets more convenient. It can also help financial institutions improve operational efficiency while maintaining required verification procedures.
2. Digital Lending Innovation
Fintech innovation is also changing the lending landscape in Pakistan.
SECP has introduced regulatory developments supporting technology-driven lending solutions. Digital lenders can use technology and API-based systems to develop new financial products and services.
These solutions can potentially improve access to credit for individuals and businesses while giving fintech companies opportunities to create innovative lending platforms.
However, responsible lending remains important. Customers should understand interest rates, fees, repayment requirements and the regulatory status of any digital lending service before using it.
3. Fintech Opportunities for Pakistani Startups
Pakistan’s startup ecosystem could benefit significantly from the growth of fintech.
Digital financial infrastructure gives startups opportunities to build solutions around payments, investment services, lending, financial management and customer onboarding.
For entrepreneurs, regulatory developments can provide a clearer environment for developing technology-based financial products. Partnerships between fintech companies, banks and regulated financial institutions could further accelerate innovation.
The combination of Pakistan’s large digital population and growing demand for convenient financial services creates considerable potential for new fintech businesses.
4. Technology and Pakistan’s Capital Markets
Technology is also becoming increasingly important for Pakistan’s capital markets.
Digital account opening, online investment platforms and API-based integration can make financial markets more accessible to a wider range of investors.
For the Pakistan Stock Exchange and other parts of the financial ecosystem, improved digital infrastructure could support greater participation and more efficient customer experiences.
As technology becomes more integrated into financial services, investors may increasingly expect faster onboarding, easier access to information and convenient digital investment tools.
5. The Future of Digital Finance in Pakistan
The future of SECP fintech will likely depend on continued cooperation between regulators, financial institutions and technology companies.
Digital finance can help improve financial inclusion and provide consumers with more convenient ways to access financial services.
At the same time, cybersecurity, consumer protection, data privacy and regulatory compliance will remain essential.
A successful digital financial ecosystem requires innovation to develop alongside appropriate safeguards.
What SECP Fintech Growth Means for Investors
For investors, fintech development could make financial services more accessible and convenient.
Digital onboarding can reduce traditional barriers to opening accounts, while technology-driven platforms can provide easier access to investment information and financial products.
However, investors should always verify that platforms and financial service providers are properly regulated. Digital convenience does not remove investment risk, and investors should conduct their own research before committing funds.
Why Fintech Matters for Pakistan
Fintech has the potential to play an important role in Pakistan’s economic development.
Millions of consumers are increasingly using smartphones and digital services, creating demand for faster payments, online investment services, digital lending and other technology-enabled financial products.
For businesses, fintech can reduce friction in financial transactions and create new opportunities to reach customers.
For consumers, it can provide greater convenience and potentially improve access to financial services.
The Road Ahead for SECP Fintech
Pakistan’s financial ecosystem is moving toward greater digital integration.
The continued development of digital investor onboarding, API connectivity, digital lending and technology-enabled financial services suggests that fintech will remain an important area of growth.
The next stage could bring even greater collaboration between regulators, banks, fintech startups, investors and technology companies.
If this digital transformation continues, Pakistan could develop a more connected financial ecosystem that supports innovation while maintaining strong regulatory protections.
Conclusion
The rise of SECP fintech is creating new possibilities for Pakistan’s financial sector. Digital investor onboarding, lending innovation, startup opportunities, capital-market technology and digital financial services are all contributing to this transformation.
For investors and businesses, these developments could create new opportunities. For fintech startups, they could provide a growing market for innovative financial solutions.
The key will be maintaining a balance between innovation, accessibility, security and regulation as Pakistan moves toward a more digital financial future.
External Links
For the article, use authoritative sources rather than random blogs:
SECP – Securities & Exchange Commission of Pakistan
SECP Fintech & Digital Finance Resources
Internal Links:
https://nz.investorbytes.com/wp-admin/post.php?post=26181&action=edit