
Central Banks Continue Building Gold Reserves
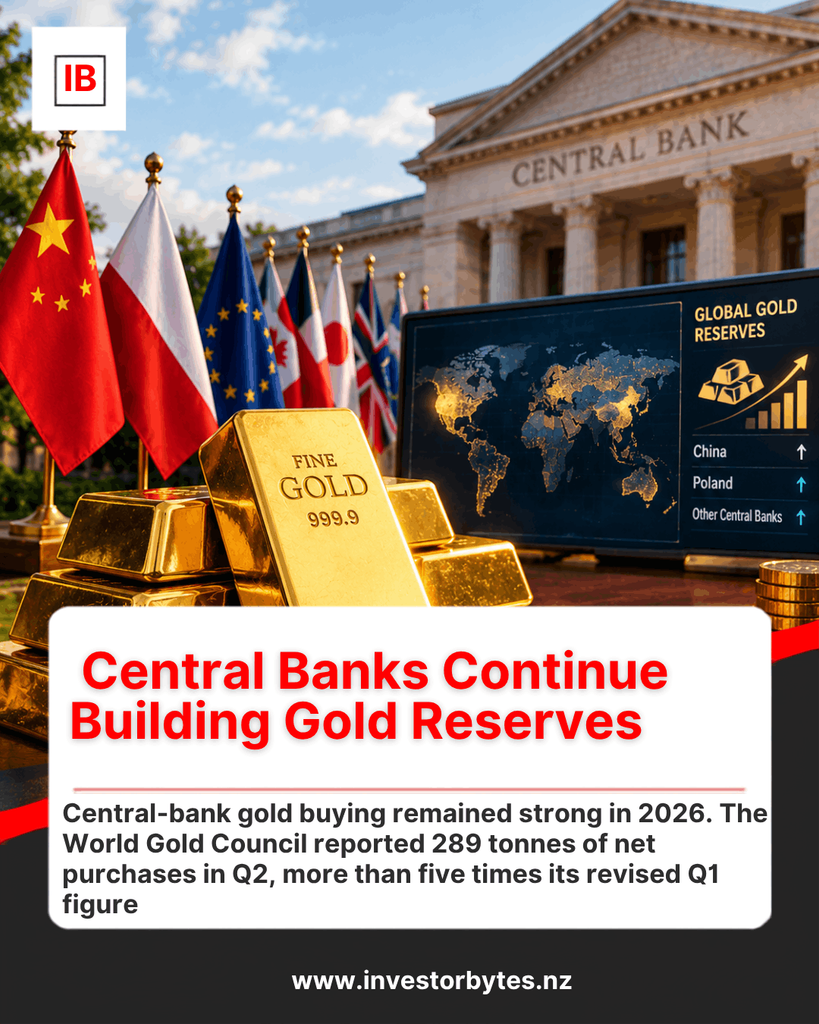
Central banks continued to accumulate gold at a strong pace during the second quarter of 2026, highlighting the metal’s growing role in official reserve management. According to the World Gold Council (WGC), central banks and other official institutions recorded 289 tonnes of net gold purchases in Q2 2026, a sharp recovery from the revised 57 tonnes recorded in Q1.
The Q2 figure was also 62% higher than the 177.9 tonnes recorded in Q2 2025, making it the strongest second quarter in the WGC’s data series. The renewed buying was supported by major purchases from Poland and China, alongside continued accumulation by several other central banks.
1. Central Bank Gold Buying Surges in Q2
The strongest signal behind Central Banks Continue Building Gold Reserves is the sharp quarterly increase in official-sector purchases.
The WGC reported net purchases of approximately 288.9 tonnes in Q2, compared with its revised Q1 estimate of 57 tonnes. This represented a more than fivefold quarterly increase.
The Q2 figure was particularly notable because gold prices remained elevated. The WGC said the LBMA gold price averaged $4,506.29 per ounce during the quarter, although this was 8% below the Q1 average.
2. Poland Leads Official Purchases
Poland was the largest reported central-bank buyer during Q2.
The National Bank of Poland added 51 tonnes during the quarter, taking its gold reserves to approximately 632 tonnes by the end of June. Its first-half purchases reached 82 tonnes, moving the country closer to its previously stated 700-tonne reserve target.
Poland’s purchases demonstrate how some reserve managers continue to use gold as part of longer-term reserve diversification strategies rather than focusing exclusively on short-term price movements.
3. China Accelerates Gold Accumulation
China was another major buyer during the quarter. The People’s Bank of China added 33 tonnes of gold in Q2, its largest quarterly addition since the fourth quarter of 2023.
The additional purchases brought China’s reported gold holdings to approximately 2,346 tonnes by the end of June.
While China’s monthly purchases were relatively modest compared with some earlier periods, the continued accumulation indicates that gold remains part of its longer-term reserve strategy.
4. Global Central Banks Remain Positive on Gold
The World Gold Council’s 2026 Central Bank Gold Reserves Survey provides another important signal.
Among surveyed central banks, 89% expected global central-bank gold reserves to increase over the following 12 months. In addition, a record 45% expected their own gold holdings to increase.
The survey covered 76 respondents and found that portfolio diversification, gold’s performance during periods of crisis, inflation hedging and geopolitical risk were among the factors supporting gold allocations.
5. Reserve Diversification Remains a Major Theme
The broader trend suggests that central banks are continuing to view gold as a strategic reserve asset.
The WGC survey found that 74% of respondents expected the US dollar’s share of global reserves to decline moderately or significantly over the next five years, while respondents expected gold’s share to increase.
This does not mean that central banks are abandoning currencies or other reserve assets. Instead, the data indicates that some institutions are seeking greater diversification across their reserve portfolios.
The WGC expects central-bank demand to remain above its long-term average in 2026, although it anticipates that full-year demand could be lower than the exceptionally strong levels recorded in 2025.
Why Central Bank Gold Buying Matters
The continued accumulation of gold by central banks can influence the global gold market because official institutions represent a significant source of structural demand.
Central banks may have different reasons for purchasing gold, including diversification, inflation protection, geopolitical risk management and long-term reserve strategy. These motivations can differ from those of short-term investors, who may react more quickly to interest rates, currencies and market sentiment.
The Q2 data is therefore important because central-bank buying remained strong even after gold prices experienced a significant correction from their first-quarter levels.
At the same time, the WGC noted that first-half central-bank demand was 345 tonnes, the lowest first-half total since 2022, partly because substantial selling by Turkey, Russia and Azerbaijan affected the Q1 figure.
Outlook for Gold Reserves
The combination of strong Q2 purchases and positive central-bank survey results points to continued interest in gold as a reserve asset.
However, individual purchasing patterns can change depending on domestic liquidity requirements, gold prices, currency conditions and broader economic developments. The WGC also noted that unreported official-sector buying remained an important feature of the market.
For investors following gold, central-bank purchases are therefore an important long-term indicator alongside Federal Reserve policy, real interest rates, the US dollar, investment flows and geopolitical developments.
Key Takeaways
- Central banks purchased 289 tonnes of gold in Q2 2026.
- Q2 purchases were more than five times the WGC’s revised Q1 figure of 57 tonnes.
- Poland was the largest reported buyer with 51 tonnes.
- China added 33 tonnes during Q2.
- 89% of surveyed central banks expected global gold reserves to rise over the following 12 months.
- A record 45% expected their own gold reserves to increase.
- Reserve diversification and geopolitical uncertainty remain important reasons for central banks holding gold.